A strong jobs report sounds like good news, and for workers and the economy it usually is.
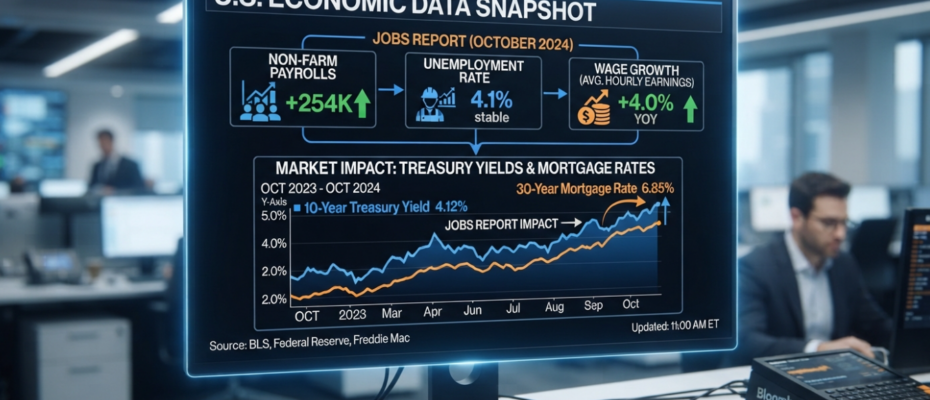
The bond market can see the same report differently. Strong hiring, low unemployment, and firm wage growth can suggest that consumer demand and inflation pressure will remain stronger. Investors may then expect the Federal Reserve to keep short term rates higher for longer, and long term Treasury yields can rise.
That can put pressure on mortgage backed securities and mortgage rates. Jobs are one of the seven forces I cover in What Really Moves Mortgage Rates.
Quick answer: A stronger than expected jobs report can push mortgage rates higher because it can raise expectations for economic growth, wage pressure, inflation, and future Federal Reserve policy. The market reaction depends on what investors expected and what the details show, not simply whether jobs increased.
What Is in the Monthly Jobs Report
The Bureau of Labor Statistics Employment Situation combines two major surveys. The establishment survey measures payroll employment, hours, and earnings by industry. The household survey measures employment status, including the unemployment rate and labor force participation.
Markets commonly focus on:
- The change in nonfarm payrolls
- The unemployment rate
- Average hourly earnings
- The average workweek
- Revisions to prior months
A headline payroll number can look strong while unemployment rises or prior months are revised lower. That is why the first market reaction can change as traders read the report.
Why Strong Hiring Can Be Tough on Bonds
Bonds pay fixed cash flows. Inflation reduces the future purchasing power of those payments, so bond investors generally demand higher yields when inflation risk increases.
A healthy labor market can support spending. Strong wage growth can also increase concern that service inflation will remain sticky. Neither outcome guarantees higher inflation, but both can change the probability investors assign to future inflation and Federal Reserve policy.
When Treasury yields rise, mortgage backed securities often weaken. Lenders may then raise rates, increase points, or reduce credits.
The Report Versus Expectations
Markets do not trade the number in isolation. They trade the difference between the report and what was already expected.
A large payroll gain may barely move rates if investors expected an even stronger number. A moderate gain can hurt bonds if the market expected weakness. Wage growth, unemployment, and revisions can also matter more than the headline payroll figure.
This is why news coverage that says rates moved because jobs were strong can be incomplete. The better question is which part of the report surprised the market.
Why a Strong Report Does Not Always Raise Mortgage Rates
Several forces can offset the jobs data. Inflation may be cooling. Oil may be falling. A Treasury auction may be strong. Investors may be buying bonds because of global risk. Mortgage backed securities may outperform Treasuries.
Sometimes the market also decides that one strong month is not enough to change the broader trend. One report matters, but no single report controls mortgage rates forever.
See how the current mix is affecting pricing on today’s St. Louis mortgage rates.
Why the Federal Reserve Cares About Employment
Congress has directed the Federal Reserve to pursue maximum employment, stable prices, and moderate long term interest rates. The Fed therefore studies a wide range of employment and inflation indicators when setting policy.
The Fed directly sets a short term policy rate, not a 30 year mortgage rate. Jobs data matter because they can change what investors expect the Fed to do next and what they expect inflation and growth to look like over time.
For a deeper explanation, read why Fed rate cuts do not directly affect mortgage rates.
What the Jobs Report Means in St Louis
The national jobs report can move mortgage pricing for a buyer in St. Louis within minutes. It does not tell you whether a specific St. Louis neighborhood suddenly became a buyer’s or seller’s market.
Local demand still depends on price range, school district, property condition, available inventory, taxes, and how many buyers are competing for the same type of home. A strong national report may raise the cost of financing while a particular seller is becoming more negotiable. Both can be true at the same time.
That is why I would rather run the actual math than react to one headline. Use the Rate Buying Power Calculator to measure the payment effect, then compare that with the price and seller credit opportunity in the local market.
What Buyers Should Do Before Jobs Day
If you are under contract and floating, know when the report will be released and what your downside looks like. Jobs data are usually released before lenders publish their first rate sheets, so the market can move before you receive a morning quote.
If today’s payment works and a worse rate would create a problem, locking may be the sensible risk decision. If you choose to float, decide in advance what would cause you to lock. Hope is not a lock strategy.
Use the Full Mortgage Payment Calculator to see the effect on principal, interest, taxes, insurance, and mortgage insurance rather than focusing only on the note rate.
The Bottom Line
A strong jobs report can be good news for the economy and difficult news for mortgage rates because bonds care about growth, wages, inflation, and future policy. The surprise relative to expectations matters more than the word strong.
Return to the seven forces that move mortgage rates for the broader framework and today’s St. Louis mortgage rates for the live market response.
Frequently Asked Questions
What Time Does the Jobs Report Come Out
The monthly Employment Situation is typically released by the Bureau of Labor Statistics at 8:30 a.m. Eastern time on its scheduled release date. Always confirm the current BLS calendar.
Which Jobs Number Matters Most for Mortgage Rates
There is no single answer. Payrolls, unemployment, wage growth, hours, participation, and prior month revisions can all affect the market. The biggest surprise often gets the most attention.
Can Weak Jobs Data Lower Mortgage Rates
It can. Weaker growth may increase demand for bonds and lower expectations for future policy rates. Inflation, oil, Treasury supply, and other risks can still offset that benefit.
Should I Lock Before a Jobs Report
That depends on your closing timeline, payment tolerance, lock options, and willingness to accept a worse outcome. If a higher payment would damage the transaction, reducing the risk may matter more than trying to catch a better rate.
Want to learn more?
What Really Moves Mortgage Rates? The 7 Forces I Watch Every Morning