*UPDATED 9/10/2026
If you have followed mortgage rates lately, you have probably noticed something frustrating: the explanation changes almost every day.
One morning it is inflation. The next it is oil. Then it is a jobs report, a Treasury auction, a Federal Reserve speech, a government bond buyback, or a geopolitical headline halfway around the world.
That does not mean mortgage rates are random. It means several markets are constantly trying to answer the same question: what will inflation, economic growth, and the value of money look like over the years ahead?
I watch this market every morning because mortgage rates are not set by a single person or a single government agency. They are ultimately the price investors demand to lend money for a long period of time, with mortgage backed securities sitting right in the middle of that process.
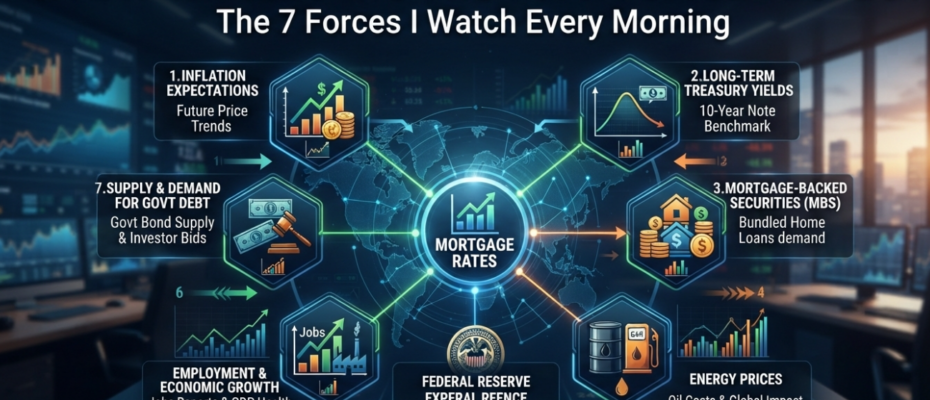
Quick answer: Mortgage rates are driven primarily by inflation expectations, long term Treasury yields, mortgage backed securities, energy prices, Federal Reserve expectations, employment and economic growth, and the supply and demand for government debt. No single factor controls rates every day.
Want to see what those forces are doing to rates right now? See today’s St. Louis mortgage rates.
1. Inflation is still the biggest long term force
Inflation matters because a mortgage is a promise to receive fixed payments years into the future. If investors believe those future dollars will buy less, they generally demand a higher return today. That pushes bond yields and mortgage rates higher.
This is why markets care so much about the Consumer Price Index, Producer Price Index, and Personal Consumption Expenditures data. But the reaction is not always as simple as a number being above or below expectations. Traders are comparing the report with what was already priced into the market, what happened inside the details, and what the report may mean for future inflation.
A report can technically be in line with expectations and still hurt bonds if traders were quietly hoping for something softer. The market trades the difference between reality and expectations, not just the headline.
Buyer resource: See how a change in mortgage rates changes buying power.
2. The 10 year Treasury is the market most people should watch first
Mortgage rates do not move exactly with the 10 year Treasury, but the 10 year is one of the best simple gauges of what is happening in the long term bond market.
When the 10 year Treasury yield rises, mortgage rates are usually under upward pressure. When Treasury yields fall, mortgage rates often improve. The relationship is not perfect because mortgages have their own risks and their own market, but it is close enough that I watch the 10 year constantly.
The important part is not just the yield itself. Technical levels matter too. When Treasury yields break through levels that traders have been defending for months or years, the move can feed on itself as investors reposition.
3. Mortgage backed securities are where mortgage rates actually live
This is the piece most consumer explanations leave out.
After many mortgages are originated, they are bundled into mortgage backed securities, often called MBS. Investors buy and sell those securities throughout the day. Lenders price new mortgage rates from that market.
That is why mortgage pricing can change at 10:00 in the morning even though the Federal Reserve did nothing and there was no new mortgage law. If MBS prices improve, lenders may be able to improve pricing. If MBS sell off, rates or lender credits can worsen.
It is also why two days with the same 10 year Treasury yield can sometimes produce slightly different mortgage pricing. The spread between Treasuries and mortgage backed securities can change based on volatility, prepayment expectations, supply, and investor demand.
4. Oil can matter much more than most homebuyers realize
Oil does not set mortgage rates, but energy prices can quickly change the inflation story.
When oil rises sharply, transportation, manufacturing, shipping, and many other costs can rise with it. Markets may begin pricing in more inflation or a Federal Reserve that has to stay restrictive for longer. That can push Treasury yields and mortgage rates higher.
The relationship is especially visible when a geopolitical event threatens energy supply. On quiet economic days, we can sometimes watch oil and Treasury yields move almost tick for tick because both markets are reacting to the same inflation concern.
Related article: Why Oil Prices Are Moving Mortgage Rates Right Now in this publishing package.
5. The Federal Reserve matters, but not the way most people think
The Federal Reserve controls a very short term interest rate. A 30 year fixed mortgage is a long term loan. Those are different markets.
So when the Fed cuts rates, mortgage rates do not automatically fall. Sometimes the bond market has already priced in the cut weeks before the meeting. Sometimes the Fed cuts because the economy is weakening and long term rates fall. Other times a Fed decision or press conference increases inflation concerns and mortgage rates rise.
What matters most is what the Fed tells markets about the future. If policymakers sound more concerned about inflation, bonds may sell off. If they signal confidence that inflation is cooling or economic growth is slowing, longer term yields can improve.
Go deeper: Why Fed rate cuts do not directly affect mortgage rates.
6. Jobs and economic growth can move rates fast
A strong economy is generally good news, but it can be bad news for bonds.
Strong employment, strong spending, and faster economic growth can keep inflation pressure alive and reduce the likelihood that the Federal Reserve will ease policy. That can push yields higher.
Weak data can have the opposite effect. If employment slows or economic activity weakens, investors may buy bonds and begin expecting lower future interest rates. That can help mortgage pricing.
Again, expectations matter. A strong jobs report may barely move rates if traders were already prepared for it. A modest miss can create a large rally if investors were positioned for something much stronger.
7. Government borrowing, Treasury supply, auctions and buybacks matter too
This has become one of the most important and least understood pieces of the rate conversation.
The U.S. government finances deficits by issuing Treasury debt. When more debt has to be sold, investors have to absorb that supply. If demand does not keep up, yields may need to rise enough to attract buyers.
Treasury auctions therefore matter. A strong auction can reassure the market that investors are willing to own government debt at current yields. A weak auction can create selling pressure.
Treasury buybacks can improve liquidity and provide temporary support in parts of the market, but buying back one set of government obligations does not erase the government’s overall borrowing need. That is why a buyback headline can help briefly without changing the longer term direction of yields.
This is an important distinction. Government action can influence market plumbing, but the market is still going to price inflation, deficits, growth, and supply and demand.
Why mortgage rates sometimes ignore the obvious headline
One of the hardest things for consumers to understand is why a seemingly huge headline occasionally produces almost no movement in rates.
Usually the answer is that markets trade expectations. If everyone knew an event was coming, much of the move may have happened before the headline. Sometimes one force also cancels out another. Weak economic data may help bonds while oil is surging. A dovish Fed comment may be offset by a poor Treasury auction.
That is why I try not to explain every market move with one sentence. The job is figuring out which force actually has control of the market that day.
What should a homebuyer actually watch?
You do not need to follow all seven of these every morning. I do.
For a homebuyer, the better question is not whether you can predict the next quarter point move. It is what today’s rate does to your payment, your buying power, and the structure of your offer.
Start with today’s published mortgage rates, then use the Rate Buying Power Calculator to see what a rate move actually means in dollars and home price.
If you are comparing lenders, use the Compare Mortgage Quotes tool so you are comparing rate, points, lender fees, and breakeven rather than just looking at a headline APR.
If payment is the problem, run the Full Mortgage Payment Calculator and the Temporary Buydown Calculator before deciding that the house or the market does not work.
My view on trying to time mortgage rates
I do not think anyone can consistently pick the exact top or bottom in mortgage rates. There are simply too many moving pieces.
I would rather make the decision with your real numbers. If today’s payment works, understand what you are locking and why. If you decide to float, understand what economic reports and market levels could change the picture. If rates improve later, refinancing may be an option. If home prices or competition change while you wait, that may be harder to undo.
The goal is not to win a guessing contest with the bond market. The goal is to make a good mortgage decision.
Soft CTA: Want to know what the market is doing today? See current Better Rate Mortgage pricing and Sean’s daily market take.
Frequently asked questions
What is the biggest factor that moves mortgage rates?
Over long periods, inflation expectations are one of the biggest drivers. Day to day, however, Treasury yields, mortgage backed securities, jobs data, oil, Federal Reserve expectations, government debt supply, and market positioning can all take control.
Why do mortgage rates follow the 10 year Treasury?
Both are long term fixed income investments that compete for investor money. Mortgage rates do not move exactly with the 10 year Treasury, but changes in long term Treasury yields are a useful signal for the direction of mortgage pricing.
Does the Federal Reserve set mortgage rates?
No. The Fed directly controls short term policy rates, not 30 year mortgage rates. Fed decisions and speeches can still move the bond market by changing expectations for inflation and future economic conditions.
Why do higher oil prices sometimes push mortgage rates higher?
A sustained increase in energy prices can raise inflation expectations. Higher expected inflation generally pressures bonds and can push longer term yields and mortgage rates higher.
What are mortgage backed securities?
Mortgage backed securities are bonds created from pools of mortgages. Investors trade them throughout the day, and lenders use that market when pricing new mortgage loans.
Should I wait for mortgage rates to fall before buying?
That depends on your payment, budget, timeline, local housing market, and risk tolerance. Waiting for a rate drop also means accepting the risk that prices, competition, or rents change while you wait. Run the numbers rather than assuming one future rate outcome.
How can I see what rates are doing today?
Better Rate Mortgage publishes representative St. Louis mortgage pricing each business morning along with Sean Zalmanoff’s daily market commentary on the mortgage rates page.
About Sean
Sean Zalmanoff is Founder and Chief Loan Officer of Better Rate Mortgage, NMLS 239823. He has spent more than 20 years originating mortgages and follows mortgage backed securities, Treasury yields, economic data, and lender pricing every business morning. Better Rate Mortgage Company NMLS 2401335.
Want to learn more?
Why Oil Prices Can Move Mortgage Rates Higher
Why the 10 Year Treasury Matters to Mortgage Rates
What Mortgage Backed Securities Actually Are and Why Homebuyers Should Care
Why Treasury Auctions Government Borrowing and Bond Supply Matter to Mortgage Rates
Why Strong Jobs Can Push Mortgage Rates Higher
Should I Lock or Float My Mortgage Rate