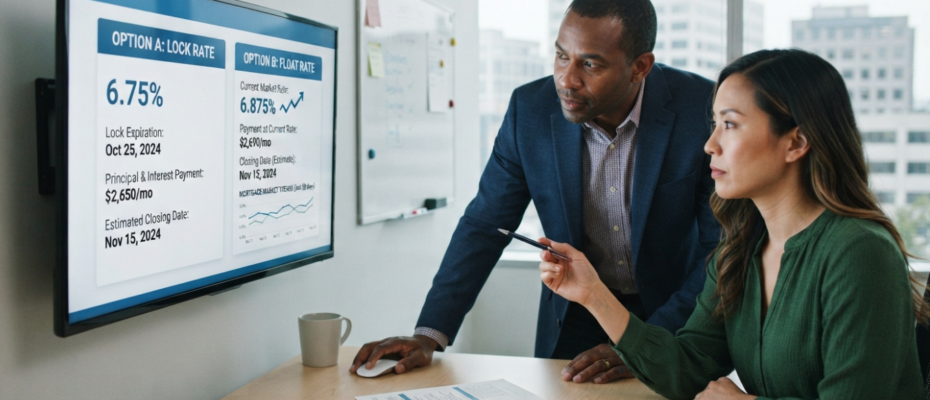
The lock or float decision is not really a prediction contest. It is a risk decision.
Locking protects an available rate for a defined period, subject to the terms of the lock and no material changes to the loan. Floating leaves the rate exposed to the market. Rates may improve, but they can also get worse before closing.
Before deciding, understand what really moves mortgage rates and then focus on the part you can control: the payment, cost, timeline, and amount of risk your transaction can absorb.
Quick answer: Consider locking when today’s payment works, the closing date fits the lock period, and a higher rate would create a meaningful problem. Consider floating only when you can tolerate a worse outcome, understand the upcoming market risks, and have a specific plan for when you will lock.
What a Mortgage Rate Lock Does
A rate lock generally means the lender agrees that the rate will not change between the lock and closing as long as the loan closes within the specified period and the application does not materially change.
Common lock periods include 30, 45, and 60 days, although shorter and longer options may be available. The pricing can vary by lock length. Longer protection can cost more because the lender is taking market risk for more time.
Your Loan Estimate should indicate whether the rate is locked and the lock expiration date. Ask for the written lock confirmation and read the conditions.
What Floating Means
Floating means the interest rate and associated points or credits are not protected. The market can move until you lock.
Floating gives you the possibility of better pricing. It also means a worse market can increase the rate, increase the cost for the same rate, or reduce lender credits. There is no guarantee that the market will give you time to react.
Five Questions I Use Before Recommending a Lock
Does Todays Payment Work
If the current payment is comfortable and a higher rate would make the home or debt ratio difficult, locking protects a workable transaction. The cost of being wrong matters more than the satisfaction of catching a slightly better rate.
How Firm Is the Closing Date
The lock should extend beyond the expected closing with a reasonable cushion. A delayed appraisal, repair, title issue, condo review, municipal requirement, or seller timing change can make a short lock expensive.
What Market Events Are Ahead
Inflation reports, jobs data, Federal Reserve meetings, Treasury auctions, and major geopolitical events can create volatility. Floating through one of them means accepting both directions of the outcome.
Can You Absorb a Worse Outcome
Run the payment at a higher rate before you float. If the downside would force a loan change, larger down payment, seller renegotiation, or canceled purchase, the risk may not be worth taking.
What Is the Actual Lock Policy
Ask how extensions work, who pays if closing is delayed, whether a float down is available, what market improvement is required, and whether loan changes can affect the lock.
When I Usually Lean Toward Locking
- The buyer is under contract and the closing timeline is known
- The current rate and payment solve the buyer’s problem
- A major market event is approaching
- The buyer has little room in the debt ratio or cash to close
- The market is volatile and the downside is larger than the likely benefit
Locking does not mean the rate is perfect. It means the buyer has decided certainty is worth more than continued exposure.
When Floating May Be Reasonable
- The borrower can comfortably absorb a worse rate
- The closing is far enough away and lock options are unattractive
- The market has a clear near term event and the borrower understands the risk
- The borrower and loan officer have a defined lock deadline and communication plan
Floating should be an intentional choice. It should not happen because nobody discussed the decision.
Why a Float Down Is Not the Same as Floating
A float down is a lender policy that may allow a locked borrower to receive some benefit if market rates improve enough. Policies vary widely. They may require a minimum improvement, a fee, a specific time before closing, or a change to current market pricing.
Do not assume a float down is automatic or free. Ask for the policy before locking.
Why the Rate Can Change Even After a Lock
A lock protects market pricing under stated conditions. It does not freeze every fact in the application.
Pricing may change if the loan amount, credit score, down payment, occupancy, property type, loan program, verified income, appraisal result, or closing date changes. The exact rules depend on the lender and lock agreement.
The St Louis Closing Timeline Matters
St. Louis contracts and properties can create timing issues that have nothing to do with the bond market. Appraisal repairs, municipal occupancy requirements, title work, condominium documents, insurance, and seller scheduling can all affect the closing date.
A fast closing can strengthen an offer, but the lock period still has to match a realistic loan process. A cheap 30 day lock is not cheaper if the transaction needs 40 days and the extension cost falls on the borrower.
Use the Cash to Close Calculator and Full Mortgage Payment Calculator to make sure both the upfront and monthly numbers work before choosing market risk.
Do Not Confuse Locking With Paying Points
Locking protects a rate and price for a period. Paying points buys a lower rate by increasing upfront cost. They are separate decisions.
A buyer can lock a no point option or lock a rate with points. The smarter comparison depends on the breakeven and how long the borrower expects to keep the loan.
Use Compare Mortgage Quotes to compare the upfront cost, monthly savings, and breakeven before paying for a lower rate.
My Practical Lock or Float Rule
If today’s terms accomplish the buyer’s goal and a worse market would hurt the deal, I lean toward protecting the deal. If the buyer floats, we define the risk, the deadline, and the communication plan first.
Nobody consistently picks the exact bottom. A good mortgage decision is one the buyer can still live with if the market moves the wrong way tomorrow.
Check today’s St. Louis mortgage rates and ask for a quote based on your actual loan before making the decision from a national average.
Frequently Asked Questions
How Long Can I Lock a Mortgage Rate
Common periods are 30, 45, and 60 days, with other terms sometimes available. Availability and pricing vary by lender, loan, and stage of the transaction.
What Happens if My Lock Expires
The lender may offer an extension, often at a cost, or apply its current relock policy. Ask who pays and how the extension is calculated before choosing the original lock period.
Can I Change Lenders After Locking
A rate lock generally applies only with the lender that issued it. Changing lenders can restart underwriting, appraisal, disclosure, and closing timelines, so compare the full transaction before making that decision.
Should I Wait for the Fed Before Locking
Not automatically. Mortgage markets often move before a Fed decision because investors trade expectations. The statement, projections, and press conference can also move long term rates in either direction.
Can My Rate Improve After I Lock
Only if the lender’s policy or a negotiated option allows it. Ask about float down terms before locking and do not assume market improvement will be passed through.
Want more insight?
What Really Moves Mortgage Rates? The 7 Forces I Watch Every Morning