A lot of St. Louis veterans start with a national VA mill because the ads are loud. That can work. It can also stall a loan on residual income, occupancy, or a condo overlay that a local originator would have flagged before you wrote the offer. A VA purchase loan uses earned VA benefits. It is not a slogan, and it is not automatic because a website said “zero down.”
Sean Zalmanoff (NMLS #239823) at Better Rate Mortgage (company NMLS #2401335) helps veterans and eligible surviving spouses compare VA, FHA, and conventional on the actual house – Clayton, Kirkwood, Webster Groves, South City, Maplewood, Chesterfield, St. Charles, and the Metro East. This is educational, not a lock or an approval. Start at betterratemortgage.com.
VA is an occupancy and residual-income product
VA wants a primary residence. If the plan is a duplex you will occupy, say that on day one. If the plan is a rental in Florissant while you stay in Kirkwood, that is not this lane.
Residual income is the quiet killer. VA looks at leftover cash after the proposed payment, taxes, insurance, and debts – not just DTI. A national mill that quotes “you qualify” from a credit pull without running residual income against St. Louis taxes and insurance is guessing.
- Bring LES or retirement plus any disability award letter you already have.
- Do not hide a car loan or a private student note. Residual income sees it later.
- Occupancy has to be real. A “I’ll move in later” story dies in underwriting.
Zero down is not zero cash in St. Louis
VA can finance 100% of the purchase price on an eligible loan. You still need cash for prepaid taxes, insurance, and closing costs unless a seller credit or gift covers them. St. Louis County, St. Charles County, and Illinois Metro East tax bills are not the same number. A Chesterfield payment and a South City payment are not interchangeable.
We write cash-to-close with actual tax and insurance quotes, not a national average. That is how buyers stop showing up short at title.
Funding fee vs monthly cost
The VA funding fee can often be financed. Whether you should finance it depends on cash, exemption status, and how long you will keep the house. A disabled veteran who is exempt should not be quoted as if the fee still applies. Ask for the exemption check before anyone “saves” you with a fee-financed payment that was never required.
We put two columns on the table: fee financed vs fee paid in cash vs conventional PMI, using your numbers. No APR promise. No “always cheaper.”
Local VA vs a national VA mill
National VA shops win on ad spend. They lose loans when a Webster Groves condo has a project issue, when a South City two-family needs occupancy math, or when residual income is tight after a truck payment. Sean’s job is not to insult another lender. It is to run the St. Louis loan as it actually underwrites.
- Certificate of Eligibility – get it early; do not wait until you are under contract.
- Property type – SFR, condo, townhome, 2-4 unit with occupancy – overlays differ.
- Repair list – VA wants livable condition. A roof that is done can fail the inspection path.
If a national shop already issued a pre-approval, bring it. We will tell you what they skipped, not what to feel about them. A pre-approval that never ran residual income against St. Louis County taxes is not a St. Louis pre-approval. It is a credit pull with a logo.
Same for condo questionnaires. If the HOA will not complete VA project questions in time, we need that answer before you waive inspections. Downtown and Central West End buildings stall here more than a Kirkwood SFR.
St. Louis geography that changes the loan
Clayton and Ladue loans often look conventional-clean. South City, Benton Park, and older Maplewood stock can trip VA condition. St. Charles new construction has builder-lender timing. Metro East (Belleville, O’Fallon, Edwardsville) is a different tax and insurance stack. We do not copy-paste a national VA checklist onto every ZIP.
Metro East loans add Illinois tax and insurance. Belleville, O’Fallon, and Edwardsville are not a St. Louis County clone. If you work in Clayton and buy in Illinois, occupancy still has to be the house, not the office.
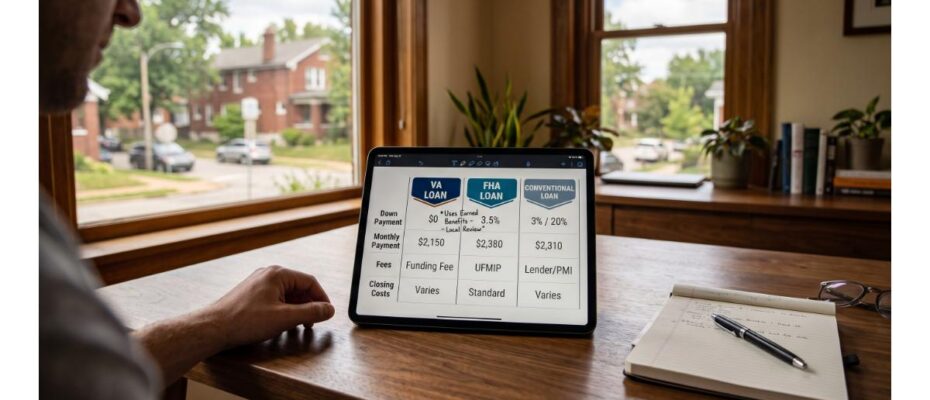
VA vs FHA vs conventional on one St. Louis offer
Use a three-column comparison:
- VA – earned benefits; often zero down; residual income; occupancy; funding fee or exemption.
- FHA – more flexible on some condition issues; typically 3.5% down; MIP structure differs.
- Conventional – often wins if you have cash, credit, and no earned VA benefit you want to use.
Leaving earned VA benefits unused because a listing agent said “conventional looks cleaner” is a costly default. We still run conventional when it is the better monthly or the property will not pass VA.
Documents to bring to the first call
LES or retirement award, COE if you have it, last two paystubs, W-2s, bank statements, and the address you want to write. If you are self-employed on the side of military income, say so immediately – that is a different underwrite.
FAQ
Can I use VA on a duplex in South City?
Often yes if you will occupy one unit and the property meets VA condition. Rent on the other unit is not a slogan – it has to underwrite.
Does a previous VA loan block a new one?
Not automatically. Remaining benefit and occupancy rules matter. Bring the old loan facts so we do not guess.
Will VA work on a short sale or REO?
Sometimes. Condition and seller timeline matter more than the listing type. We check before you write.
Should I skip VA because I heard the funding fee is high?
Run the exemption check and the monthly comparison first. Skipping VA from a rumor is how people pay PMI they did not need.
Next step
Start a VA purchase review at betterratemortgage.com. Bring COE or enough service facts to pull one, the target ZIP, and residual-income documents. Sean will tell you if VA, FHA, or conventional is the loan that can actually close.
Sean Zalmanoff – Better Rate Mortgage – St. Louis, MO – NMLS #239823
Equal Housing Opportunity. Sean Zalmanoff, NMLS #239823. Better Rate Mortgage, Company NMLS 2401335. Educational content only, not a commitment to lend. VA eligibility and residual income are determined under current program rules. All loans subject to credit approval, property eligibility, and lender guidelines. Verify licensing at NMLS Consumer Access.