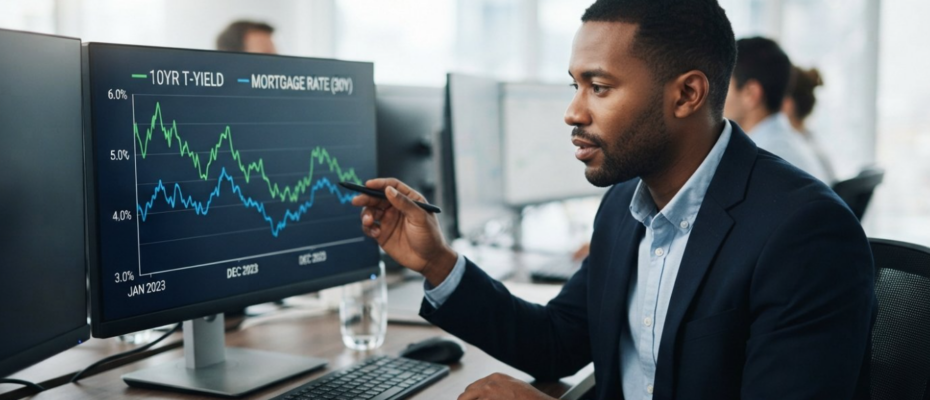
If someone asks what mortgage rates are doing, the 10 year Treasury yield is usually one of the first numbers I check.
It is public, it moves throughout the trading day, and it gives us a fast read on how investors are pricing inflation, economic growth, Federal Reserve expectations, and the demand for long term bonds.
It is still only one part of the picture. Mortgage rates are priced more directly from mortgage backed securities, which is why I use the 10 year as a guide rather than a promise. For the full framework, read what really moves mortgage rates.
Quick answer: Mortgage rates often move in the same direction as the 10 year Treasury because both compete for long term investor money. When the 10 year yield rises, mortgage rates usually face upward pressure. When it falls, mortgage pricing often improves. The spread between the two can widen or narrow, so they do not move point for point.
Why a 30 Year Mortgage Follows a 10 Year Treasury
The names make this sound strange. A 30 year fixed mortgage lasts up to 30 years, while a 10 year Treasury matures in 10 years.
In practice, most mortgages do not remain outstanding for the full 30 years. Homeowners sell, refinance, pay extra principal, or otherwise pay off the loan early. Investors therefore compare many mortgage cash flows with intermediate and long term Treasury securities, with the 10 year becoming the most familiar public benchmark.
That does not mean a mortgage has a fixed 10 year life. Its expected life changes as rates and borrower behavior change. That uncertainty is one reason mortgage rates normally sit above Treasury yields.
What the 10 Year Yield Is Telling Us
A Treasury yield is the return investors demand to lend money to the federal government for a stated period. The 10 year yield reflects several forces at once:
- Expected inflation over the years ahead
- Expected economic growth and future short term rates
- Demand for safe, liquid U.S. government debt
- The amount of Treasury debt the market must absorb
- Global risk, currency demand, and investor positioning
When investors become more worried about inflation or believe the economy will stay stronger for longer, they may demand a higher yield. When growth fears rise or investors seek safety, they may buy Treasuries and push yields lower.
Want to see how the bond market is showing up in actual pricing? Check today’s St. Louis mortgage rates.
Price and Yield Move in Opposite Directions
This is the part that confuses almost everyone at first. When investors buy a lot of existing Treasury bonds, bond prices rise and yields fall. When investors sell, prices fall and yields rise.
That is why a bond market rally is generally good for mortgage rates, while a bond selloff is generally bad. Mortgage backed securities work with the same basic price and yield relationship.
Why Mortgage Rates Do Not Match the 10 Year Exactly
A Treasury security is backed by the federal government and has a set maturity. A mortgage backed security carries different cash flow and prepayment characteristics. Investors need additional yield to accept those differences.
The gap between mortgage rates and the 10 year Treasury is often called the mortgage spread. It can change because of market volatility, expected refinancing, demand for mortgage bonds, lender capacity, servicing value, guarantee fees, and competition among lenders.
Two days can have the same 10 year yield and still produce different mortgage pricing. That is not a contradiction. It usually means the mortgage backed securities market or lender margins changed relative to Treasuries.
Why Technical Levels Can Matter
Bond traders watch certain yield levels because a break above or below them can trigger repositioning. A level that held for months may attract buyers the first few times it is tested. If it finally breaks, selling can accelerate.
This is useful context for a lock decision, but it is not fortune telling. A technical level can fail after one inflation report, jobs report, oil move, Treasury auction, or unexpected headline.
What This Means for a St Louis Buyer
The Treasury market is national. The decision it creates is local.
A rate move can change the payment enough to alter the price range that works, but St. Louis is not one market. A small payment change may matter differently for a first time buyer shopping in South City than for a move up buyer comparing Kirkwood, Webster Groves, or Chesterfield. Inventory, taxes, insurance, property condition, and seller flexibility all affect the real decision.
Use the Rate Buying Power Calculator to see what a change in rate does to the home price supported by the same payment. Then use the St. Louis Affordability Map to compare where that payment may fit.
What Buyers Should Watch Instead of Guessing
You do not need to trade Treasury bonds from your phone. You need to know whether the market is stable, improving, or becoming more volatile while you are under contract.
If today’s payment works and the closing date is firm, locking removes one major risk. If you float, do it with a reason, a deadline, and a clear understanding of which reports could move the market.
Before making that call, read Should I Lock or Float My Mortgage Rate once it is live, and compare the full payment with the accurate mortgage payment calculator.
The Bottom Line
The 10 year Treasury is one of the best public gauges of mortgage rate direction, but it is not a retail mortgage rate sheet. It tells us what the broader bond market is doing. Mortgage backed securities and lender pricing determine how much of that move reaches a borrower.
For the complete picture, return to the seven forces that move mortgage rates and check today’s St. Louis mortgage rates for the live version.
Frequently Asked Questions
Do Mortgage Rates Always Move With the 10 Year Treasury
No. They usually move in the same direction over time, but the spread between Treasuries and mortgage backed securities can change. Lender margins and loan specific pricing also matter.
Why Not Watch the 30 Year Treasury
A 30 year mortgage rarely remains outstanding for the full term because borrowers sell, refinance, or pay it off early. The 10 year Treasury has become the most familiar public benchmark for the intermediate and long term market that mortgages compete within.
Does a Lower 10 Year Yield Guarantee a Better Mortgage Quote
No. It usually helps the backdrop, but mortgage backed securities, lender repricing, points, credit, down payment, occupancy, property type, and lock period can all affect the quote.
How Fast Can Mortgage Pricing React
Mortgage backed securities trade throughout the day, and lenders can reprice when the market moves enough. A quote from the morning may not remain available later unless it is locked.
Want to learn more about what really mortgage rates? https://betterratemortgage.com/what-actually-drives-mortgage-rates-higher-or-lower/
About Sean
Sean Zalmanoff is Founder and Chief Loan Officer of Better Rate Mortgage, NMLS 239823. He has spent more than 20 years originating mortgages and follows mortgage backed securities, Treasury yields, economic data, and lender pricing every business morning. Better Rate Mortgage Company NMLS 2401335.